Shareholders’ equity is one of the most important figures for judging how solid a company is from a balance sheet standpoint. It is usually looked at after revenue, net income and EBITDA (earnings before interest, taxes, depreciation and amortization), but it carries a different and fundamental piece of information: it shows how much of the company’s resources is funded with its own money rather than with someone else’s.
A company can post high revenue and healthy margins and still be fragile if its equity is very low or negative. That is why, when you read a company’s financial statements, equity is one of the figures to check in order to assess balance, staying power and the ability to get through a rough patch.
What shareholders’ equity is
In simplified terms, shareholders’ equity is the difference between what a company owns and what it owes to third parties.
Put another way, it is the portion of the company’s assets that belongs to the business and its shareholders once debts and other liabilities have been accounted for.
The basic formula is:
Shareholders’ equity = Assets - Liabilities
Assets include property, receivables, cash and cash equivalents, fixed assets and the company’s other resources. Liabilities include amounts owed to banks, suppliers, tax authorities, employees and other parties.
If assets exceed liabilities, equity is positive. If liabilities exceed assets, equity can turn negative, a signal that calls for closer scrutiny.
Where shareholders’ equity sits on the balance sheet
Equity appears on the balance sheet (stato patrimoniale), one of the main sections of a company’s annual accounts.
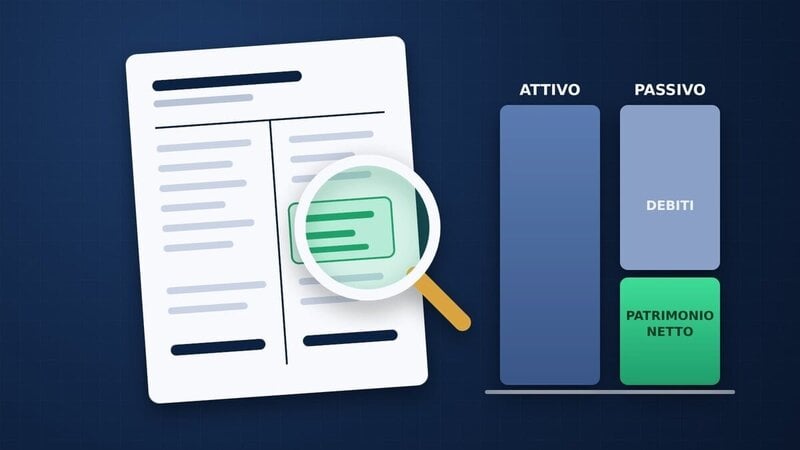
The balance sheet shows how the company’s resources are composed at the close of the fiscal year: assets on one side, liabilities and equity on the other.
In Italian statutory accounts (the bilancio civilistico, the format prescribed by the Italian Civil Code), equity is reported among the items on the liability side of the balance sheet. The same convention applies under US GAAP and IFRS, where the balance sheet reads Assets = Liabilities + Shareholders’ Equity. It can feel counterintuitive, because in everyday language “net worth” sounds like something that belongs on the positive side. In accounting, though, the liability side lists the company’s sources of funding: where the resources used to run the business come from.
Those sources are of two kinds:
- own funds, meaning shareholders’ equity;
- outside funds, meaning debt and other liabilities.
That is why equity sits on the liability side: it represents an internal source of funding for the company.
What shareholders’ equity is made of
Equity is not a single undifferentiated line. Several components can sit inside it, and they help clarify how the company is structured.
The main ones are:
- share capital;
- reserves;
- retained earnings or accumulated losses carried forward;
- profit or loss for the year;
- other reserves required by law or by the company’s bylaws.
Share capital represents the value contributed by shareholders when the company was formed or in subsequent capital increases.
Reserves are portions of equity set aside over time, often derived from undistributed profits or from specific corporate transactions.
Retained earnings and accumulated losses carried forward reflect results from prior years that have not yet been allocated or absorbed.
Profit or loss for the year shows the result of the year just closed, which will in turn feed into equity.
What shareholders’ equity tells you about a company
Equity helps you understand how far a company is supported by its own resources. A positive figure that is adequate relative to the size of the business can indicate a greater capacity to absorb losses, invest, obtain credit and weather difficult stretches.
Very thin equity, by contrast, can signal a fragile capital structure. That does not automatically mean the company is in distress, but it does mean the rest of the financial statements deserve a careful read.
Equity is useful for answering questions such as:
- does the company have a solid capital base?
- is it heavily dependent on debt?
- has it accumulated profits or losses over time?
- can it absorb a negative result?
- is its structure consistent with its revenue, its industry and its size?
For example, a company with high revenue but very thin equity may be more exposed to financial strain than one with lower revenue and sturdier own funds.
Positive shareholders’ equity: what it means
Positive equity means the company’s assets exceed its liabilities. In general terms it is a favorable signal, because it shows the business has own funds behind it.
Positive is not enough on its own, though: the figure also has to be adequate relative to the scale of the business.
Equity of €100,000 (about $108,000) may be sufficient for a small services firm, but very limited for an industrial company with high revenue, a large headcount, significant capital spending and heavy exposure to banks or suppliers.
That is why equity should always be compared against:
- total assets;
- debt;
- revenue;
- profit or loss;
- the industry the company operates in;
- the trend over prior years.
The absolute number matters, but its relationship to the rest of the financial statements matters more.
Negative shareholders’ equity: when it is a red flag
Equity turns negative when liabilities exceed assets. It is a delicate situation, because it can indicate that the company has eroded its own funds, often through accumulated losses.
Negative equity should not be read automatically as imminent failure, but it is certainly a signal that warrants digging further.
It can stem from:
- repeated annual losses;
- extraordinary costs;
- an industry downturn;
- heavy indebtedness;
- write-downs in the value of certain assets;
- a restructuring phase.
When you come across negative equity, it is worth checking whether the company has recapitalization plans, whether the latest annual result improved or deteriorated, and whether the situation is temporary or structural.
For anyone assessing a customer, a supplier or a commercial partner, this figure calls for caution: before entering into any significant relationship, it is worth also reading the financial statements, the company registry history (in Italy, the visura storica, the Chamber of Commerce record of a company’s changes over time) and any other available documents.
Shareholders’ equity and share capital: what is the difference
Shareholders’ equity and share capital are not the same thing.
Share capital is one component of equity and represents the capital contributed by shareholders. Equity is a broader measure that also includes reserves, undistributed profits, accumulated losses and the result for the year.
A company can have low share capital but high equity if it has accumulated profits and reserves over the years. Conversely, it can have share capital formally in place but reduced or negative equity if it has booked significant losses.
So when you are assessing how solid a company is, share capital alone is not the number to look at. Total equity gives a more useful reading of the capital structure.
How to use shareholders’ equity to assess a company
Equity becomes more useful when it is read alongside the other figures in the financial statements.
On its own it is not enough to say whether a business is solid or fragile. A company can have high equity and weak profitability, or modest equity with growing margins and low debt.
For a fuller assessment, it is worth looking at:
- equity against debt;
- equity against total assets;
- equity against revenue;
- equity against net income;
- the trend in equity over recent years;
- a comparison with companies in the same industry.
If equity grows over time, it can indicate that the company is retaining profits and strengthening its structure. If it shrinks year after year, it can signal losses, substantial distributions to shareholders or a weakening capital base.
Where to find equity and balance sheet data
Equity is one of the figures to watch in order to understand how solid a company is, but it should never be read in isolation. It takes on meaning when it is compared with debt, revenue, profit, the industry and the trend over time: only then can it help you tell whether a business has a balanced capital structure or shows elements that need a closer look.
For listed companies, equity is reported in the annual and quarterly filings — the 10-K and 10-Q in the United States, the annual and half-year reports elsewhere. For private companies, the figures come from the filings lodged with the national business register.
For Italian companies specifically, that data is held by the Chamber of Commerce registry and can be consulted through Money Aziende, the Money.it platform dedicated to official company records, which lets you search a business by name or VAT number and pull figures such as revenue, EBITDA, net income, registered office, legal form and the latest available financial statements, as well as order official registry documents.
Editor’s note
This article was originally published in Italian on money.it by Redazione Imprese on October 18, 2026 as «Patrimonio netto. Cos’è, dove si trova nel bilancio e cosa dice su un’azienda». It has been translated and adapted for an international audience by the Money.it International desk.